Founded by Immad Akhund, Jason Zhang and Max Tagher, Mercury has evolved from a digital banking platform for startups into a broader financial technology business, securing new investment and pursuing a U.S. national bank charter.
Mercury, the U.S. financial technology company known for providing digital banking services to startups and small businesses, is entering a new phase of growth as it expands its financial products, attracts additional venture capital and pursues a national bank charter.
Founded in 2017 by Immad Akhund, Jason Zhang and Max Tagher, the company has built a platform combining business banking access, payments, corporate cards, treasury management and financial operations software. In May 2026, Mercury announced a $200 million financing round at a $5.2 billion valuation, extending its growth beyond the $3.5 billion valuation established in March 2025.
The expansion reflects Mercury’s ambition to move beyond its original position as a banking platform for technology startups and become a more comprehensive financial services provider for businesses and individuals.
How Mercury’s Founders Identified an Opportunity in Business Banking
Mercury was established to address a persistent problem for entrepreneurs: traditional business banking systems often require founders to manage financial activities across separate institutions, software products and administrative processes.
Co-founder and chief executive Immad Akhund brought experience in software development and entrepreneurship. Before Mercury, he founded the mobile advertising startup Heyzap, which was acquired in 2016 for a reported $45 million.
Akhund partnered with Jason Zhang, Mercury’s chief operating officer, and Max Tagher, its chief technology officer. Both had previously worked with him, giving the founding team an established working relationship before entering financial technology.
The founders approached banking as a software and product design challenge, seeking to make essential financial operations more accessible to businesses accustomed to modern digital tools.
Mercury initially concentrated on startup banking, where newly established companies frequently need to open accounts, receive investor funds, manage payments and control spending without the infrastructure of a large finance department.
That focus helped the company develop relationships within the startup ecosystem before expanding its services to a wider business audience.
Mercury’s Integrated Financial Platform for Startups and Businesses
Mercury’s business model centres on combining access to banking services with financial management software.
Through its platform, businesses can access checking and savings accounts, debit and corporate cards, payment processing, invoicing, bill payments, treasury products and accounting-related automation.
Rather than operating solely as a traditional financial institution, Mercury has historically delivered its services through relationships with regulated partner banks while developing and managing the customer-facing technology.
This distinction is important. Mercury’s fintech services are not themselves equivalent to an FDIC-insured bank. Eligible deposits are held at partner institutions, where deposit insurance applies subject to the relevant coverage rules and conditions.
According to Mercury’s company overview, its product strategy is to bring financial activities into a unified environment, allowing customers to manage payments, spending, cash flow and related operations without moving between numerous providers.
The approach also positions Mercury in competition with financial software companies offering corporate spending, accounts payable and financial management products.
As businesses grow, the value of an integrated platform increasingly depends on its ability to support more complex financial workflows while maintaining reliability and regulatory compliance.
Mercury’s Funding Growth and Rising Valuation
Mercury’s venture capital financing has provided resources for product development, customer acquisition and expansion into additional financial services.
In March 2025, the company announced a $300 million Series C financing comprising primary and secondary investment. The round was led by Sequoia Capital, with participation from Spark Capital, Marathon, Coatue, CRV and Andreessen Horowitz.
The transaction valued Mercury at $3.5 billion and brought its reported cumulative primary and secondary financing to approximately $500 million.
In May 2026, Mercury secured another $200 million in a Series D financing led by TCV, lifting its valuation to $5.2 billion. The new valuation represented an increase of approximately 49% over its March 2025 level.
The investment demonstrates continued investor interest in fintech companies that combine financial services distribution with recurring customer relationships and software-based financial operations.
Mercury’s financing history also illustrates its transition from a venture-backed startup primarily focused on customer acquisition to a larger financial technology business with an established revenue base.
Revenue Growth and Sustained Profitability
Mercury’s financial performance has become a significant part of its growth story.
The company reported reaching $650 million in annualised revenue during the third quarter of 2025, compared with an annualised figure of $500 million at the end of 2024.
These figures represent revenue run rates rather than audited full-year revenue totals. Mercury calculates annualised revenue by multiplying monthly revenue by 12, according to reporting by Fortune.
The company also reported three consecutive years of profitability under generally accepted accounting principles through 2025. Its May 2026 financing announcement subsequently cited four consecutive years of GAAP net income and EBITDA profitability.
These results distinguish Mercury from earlier-stage fintech businesses that continue to prioritise expansion while operating at a loss.
However, annualised revenue and profitability alone do not fully describe the company’s financial position. As Mercury pursues a bank charter, capital requirements, regulatory costs and the economics of its expanding product portfolio will become increasingly important.
Mercury’s National Bank Charter Ambitions
One of Mercury’s most consequential strategic developments came in December 2025, when it submitted an application to the Office of the Comptroller of the Currency for a national bank charter and separately applied to the Federal Deposit Insurance Corporation for federal deposit insurance.
The applications marked a potential shift from Mercury’s longstanding model of delivering financial technology services through partner banks toward operating its own regulated banking institution.
The distinction carries significant implications for the company’s future.
A national bank charter could give Mercury greater direct control over banking operations and product development. It would also introduce additional responsibilities involving capital adequacy, risk management, compliance and regulatory supervision.
In May 2026, Mercury received conditional regulatory approval to establish Mercury Bank, an important step toward becoming a nationally chartered institution. Conditional approval, however, does not mean the company has completed every requirement necessary to begin operating independently as an insured bank.
The move places Mercury among financial technology businesses seeking a more direct role in regulated banking rather than remaining exclusively technology intermediaries.
Mercury’s Position in the Evolving Fintech Industry
Mercury’s growth reflects broader changes in how startups and small businesses manage their finances.
Business customers increasingly expect banking, payments, expense management, invoicing and financial reporting to operate together rather than as disconnected services.
This has intensified competition among digital banking providers, corporate card platforms, financial automation companies and established financial institutions.
Mercury’s integrated approach gives it an opportunity to serve a larger portion of a customer’s financial operations. It also creates pressure to continue improving product reliability, security, compliance and customer support as the company scales.
In its May 2026 announcement, Mercury reported serving more than 300,000 customers and said that over 73% of new customers came from outside the AI and technology startup category.
That customer mix is particularly significant because it indicates that Mercury’s growth is no longer dependent exclusively on venture-backed technology companies.
Its expansion into ecommerce, professional services and personal finance suggests a broader addressable market, although serving these segments requires products that accommodate different financial needs and business structures.
What’s Next for Mercury?
Mercury’s next phase will be shaped by the development of its regulated banking operations, the continued expansion of its financial software platform and its ability to sustain profitable growth.
The company’s progress from startup-focused banking software to a multibillion-dollar fintech business illustrates how specialised financial products can evolve into broader financial infrastructure.
For Akhund, Zhang and Tagher, the strategic challenge is now more complex than building a convenient alternative to traditional business banking. Mercury must balance product innovation and expansion with the operational and regulatory requirements of a larger financial institution.
Its progress toward a national bank charter could become a defining milestone, but the long-term outcome will depend on regulatory execution, financial performance and the company’s ability to maintain customer trust as its responsibilities increase.
Related Stories
Elorian Unveils Glimpse After Raising $55 Million for Visual AI Development
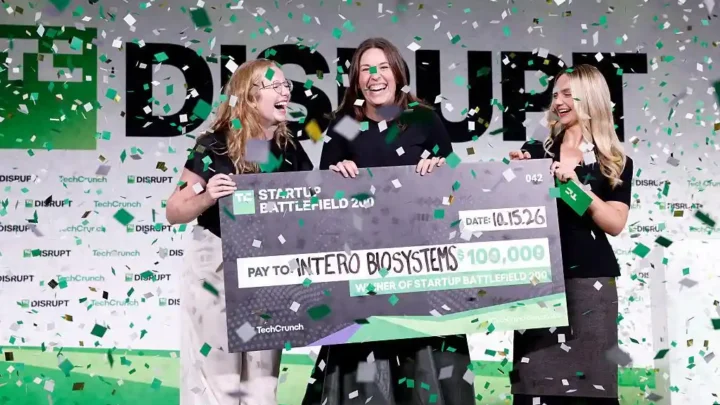
Intero Biosystems Wins TechCrunch Disrupt 2026 Startup Battlefield and $100,000 Prize
Dublin International AI Summit 2026 Hosts Global Leaders to Address AI Innovation, Safety and Regulation